DSCR in Project Finance: How Lenders Use LLCR and PLCR
How do lenders use DSCR, LLCR and PLCR? Learn how these project finance ratios influence debt sizing, repayment, covenants and lender decisions.
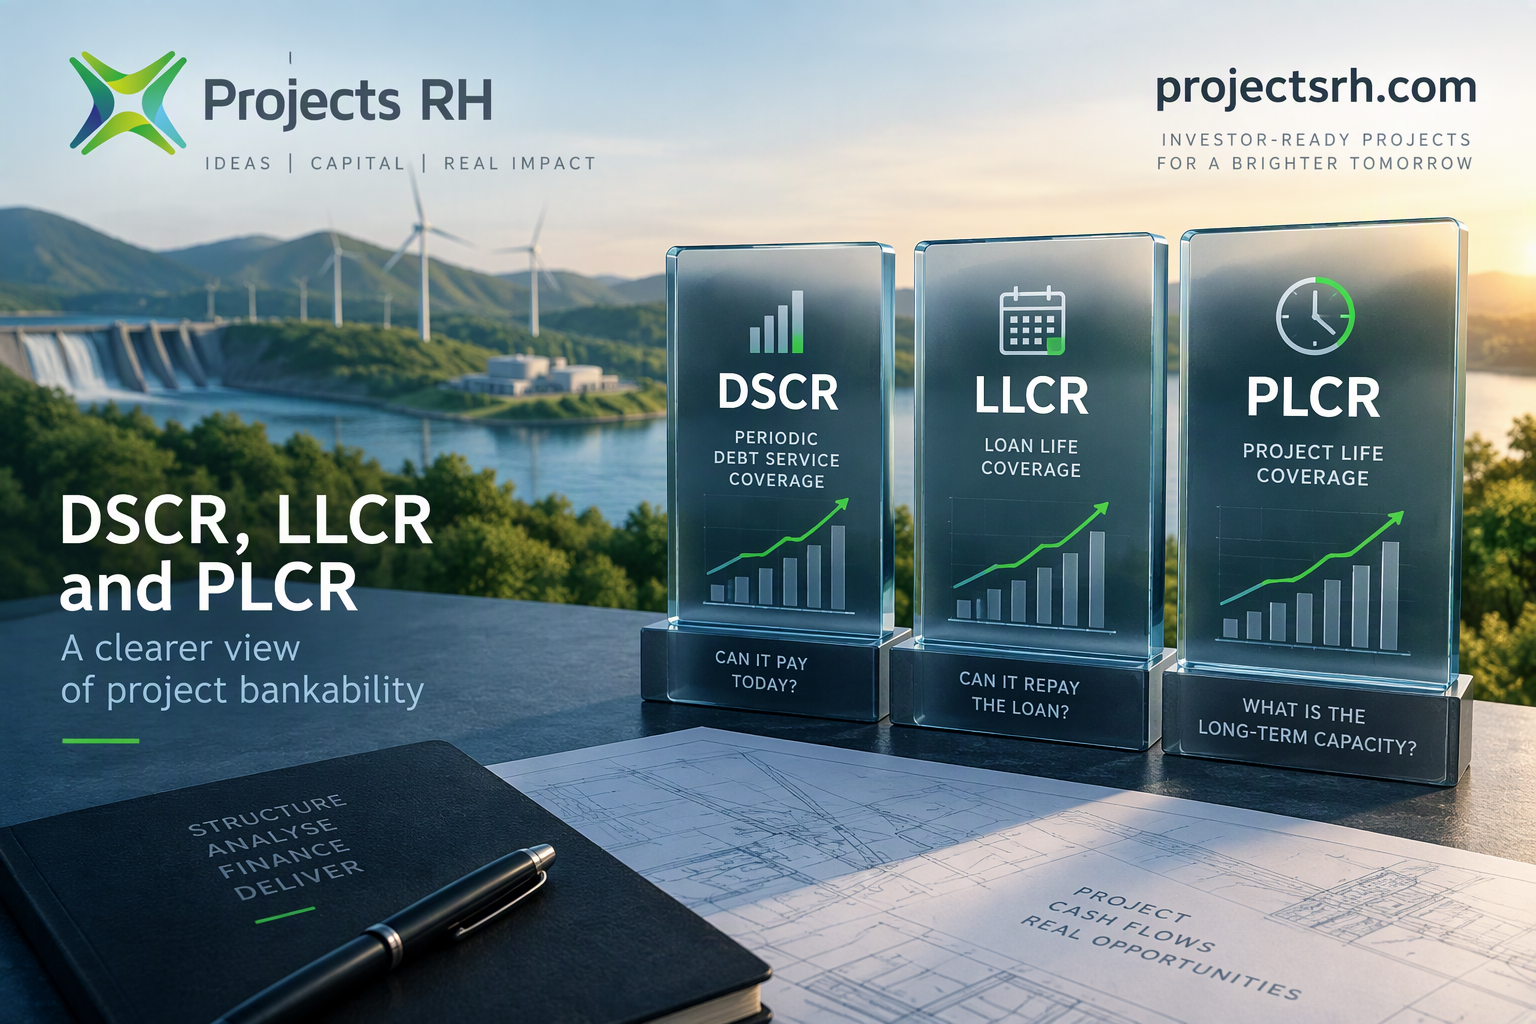
DSCR in Project Finance is one of the first metrics lenders examine when deciding how much debt a project can realistically support.
But it is not the only one.
A project can show an acceptable Debt Service Coverage Ratio in the next twelve months while presenting a much weaker credit story across the remaining loan life.
That is why sophisticated project finance analysis often goes further.
Lenders may consider three related but different coverage ratios:
- DSCR — Debt Service Coverage Ratio
- LLCR — Loan Life Coverage Ratio
- PLCR — Project Life Coverage Ratio
Each answers a different question.
DSCR asks whether the project can service debt in a particular period. LLCR asks whether discounted cash flows over the remaining loan life can cover outstanding debt. PLCR extends that analysis through the remaining economic life of the project.
Throughout my career in finance, resources, energy and project development, I have found that sponsors often focus on the ratio that looks strongest.
Lenders tend to focus on the ratio that reveals the risk.
That difference matters.
Understanding DSCR in Project Finance, together with LLCR and PLCR, provides a much clearer view of how lenders think about debt capacity, amortisation, covenant protection, refinancing risk and financial resilience.
What Is DSCR in Project Finance?
DSCR in Project Finance measures the amount of Cash Flow Available for Debt Service generated during a specified period relative to the principal and interest payable during that same period.
In simplified form:
DSCR = CFADS ÷ Debt Service
Where:
- CFADS = Cash Flow Available for Debt Service
- Debt Service = scheduled principal + interest for the relevant period
For example:
CFADS = $15 million
Principal + Interest = $10 million
Therefore:
DSCR = $15 million ÷ $10 million = 1.50x
A DSCR of 1.50x means the project generates $1.50 of cash available for every $1.00 of scheduled debt service during that period.
A DSCR of 1.00x means there is precisely enough cash to meet debt service, with no coverage headroom.
Below 1.00x, operating cash available for debt service is insufficient to meet scheduled debt obligations for that period.
Forvis Mazars' project finance modelling guidance similarly defines DSCR as CFADS divided by debt service and explains its use in loan sizing, repayment sculpting and covenant monitoring.
Why CFADS Matters More Than EBITDA
Project finance is fundamentally cash-flow lending.
For that reason, lenders are not simply interested in EBITDA.
They need to establish how much cash genuinely remains available to service debt after the project-level cash requirements recognised by the financing structure.
A simplified CFADS bridge might therefore look conceptually like:
Revenue
– Operating Costs
– Cash Taxes
– Maintenance / Required Capital Expenditure
± Working Capital Movements
= CFADS
The exact definition depends on the particular transaction and financing documents.
This matters enormously.
A project can report attractive accounting earnings while producing substantially less cash available for lenders.
Project finance debt is repaid with cash, not accounting profit.
For that reason, the contractual definition of CFADS should reconcile with the financial model.
The Three Questions Lenders Are Really Asking
DSCR, LLCR and PLCR can be understood through three simple questions.
DSCR
Can the project pay the debt due during this period?
LLCR
Can the project's discounted cash flows through final loan maturity support the outstanding debt?
PLCR
Can the project's discounted cash flows through the remaining project life support the outstanding debt?
This distinction between periodic, loan-life and project-life coverage is also reflected in specialist project finance literature comparing the three ratios. Oxxon Advisors' comparison describes DSCR as the single-period measure, LLCR as the remaining-loan-life measure and PLCR as the measure extending through the project's remaining useful life.
The ratios therefore complement rather than replace one another.
What Is LLCR?
LLCR means Loan Life Coverage Ratio.
LLCR measures the present value of projected Cash Flow Available for Debt Service over the remaining life of the loan relative to the amount of debt outstanding at the measurement date.
In simplified form:
LLCR = NPV of CFADS During Remaining Loan Life ÷ Outstanding Debt
Suppose:
- outstanding debt is $100 million;
- the present value of eligible CFADS through loan maturity is $150 million.
Then:
LLCR = $150 million ÷ $100 million = 1.50x
This gives lenders a longer-term view than DSCR.
The Corporate Finance Institute's LLCR guidance similarly describes LLCR as the net present value of CFADS through debt maturity divided by outstanding debt.
Why LLCR Can Reveal What DSCR Misses
Imagine a project with a healthy DSCR next year.
That looks reassuring.
But suppose projected cash flows deteriorate significantly five years later because:
- an offtake agreement expires;
- operating costs rise;
- major maintenance becomes necessary;
- production declines;
- customer contracts roll off;
- commodity assumptions weaken; or
- equipment needs replacement.
The next-period DSCR may still look comfortable.
LLCR can reveal the more structural problem.
That is precisely why these ratios should not be viewed in isolation.
DSCR provides a periodic photograph. LLCR provides a view across the remaining loan horizon.
What Is PLCR?
PLCR means Project Life Coverage Ratio.
PLCR measures the present value of projected CFADS over the remaining economic life of the project relative to outstanding debt.
In simplified form:
PLCR = NPV of CFADS During Remaining Project Life ÷ Outstanding Debt
The difference from LLCR is largely the cash-flow horizon.
LLCR stops at loan maturity.
PLCR continues through the relevant remaining project life.
The Corporate Finance Institute's PLCR guidance describes PLCR as a measure used to determine the repayment capacity of project cash flows over the project's life and notes that it is commonly considered alongside DSCR and LLCR.
Why PLCR Is Usually Different From LLCR
Consider a 25-year infrastructure asset financed with debt maturing after 18 years.
That leaves a seven-year period after scheduled debt maturity.
This is commonly referred to as the debt tail.
Those additional seven years of potential cash generation appear in PLCR but not LLCR.
That means:
Loan Life < Project Life
and typically:
PLCR > LLCR
assuming positive post-maturity CFADS under equivalent modelling assumptions.
The difference can provide lenders with additional evidence of refinancing or restructuring capacity.
But that apparent protection needs scrutiny.
Future cash flows may be affected by:
- concession expiry;
- asset degradation;
- technology obsolescence;
- declining production;
- contract expiry;
- regulatory change;
- maintenance expenditure; or
- uncertain residual value.
A long debt tail has little value if the underlying cash flows are not credible.
DSCR vs LLCR vs PLCR
The cleanest comparison is:
| Ratio | Question | Measurement horizon | Core use | |---|---|---|---| | DSCR | Can debt service be paid in this period? | Individual debt-service period | Repayment capacity, covenants and sculpting | | LLCR | Can remaining loan-life cash flow cover debt? | Remaining loan tenor | Debt capacity and structural credit analysis | | PLCR | Can remaining project-life cash flow cover debt? | Remaining project life | Long-term coverage and debt-tail analysis |
Although the formulas appear simple, the assumptions behind them are not.
A lender needs confidence in:
- CFADS;
- debt balance;
- interest assumptions;
- discount rate;
- loan maturity;
- project life;
- reserves;
- major maintenance;
- termination assumptions; and
- downside scenarios.
That is where project finance modelling becomes credit analysis rather than arithmetic.
How Lenders Use DSCR for Debt Sizing
Suppose annual CFADS is projected at:
$15 million
and the lender requires a target DSCR of:
1.50x
Maximum debt service supported in that period would be:
$15 million ÷ 1.50 = $10 million
If interest for the period is:
$4 million
the remaining amount available for scheduled principal would be:
$6 million
This logic forms part of debt sculpting.
Instead of imposing a completely flat principal repayment profile, the debt schedule can be shaped around expected CFADS while preserving a defined coverage ratio.
When cash flow is stronger, more debt can potentially be repaid.
When cash flow is weaker, scheduled repayment may need to decline.
That creates a closer relationship between the project's economics and its financing obligations.
What Is Debt Sculpting?
Debt sculpting is the process of shaping scheduled principal repayments around forecast project cash flows so that debt service remains consistent with a defined target coverage ratio.
A simplified relationship is:
Permitted Debt Service = CFADS ÷ Target DSCR
then:
Principal Repayment = Permitted Debt Service – Interest
Of course, an actual project finance model can be considerably more complex.
It may need to consider:
- tax;
- multiple debt facilities;
- variable interest rates;
- reserve movements;
- repayment frequency;
- grace periods;
- cash sweeps;
- refinancing;
- hedging;
- circular calculations; and
- different covenant definitions.
But the underlying objective remains familiar:
Match the repayment profile to the project's capacity to generate cash without removing the lender's required coverage cushion.
A Worked DSCR Example
Consider a project with:
- annual CFADS: $24 million
- scheduled interest: $6 million
- scheduled principal: $10 million
Total debt service:
$16 million
Therefore:
DSCR = $24 million ÷ $16 million = 1.50x
Now assume a downside case reduces CFADS by 20%.
Downside CFADS becomes:
$19.2 million
Debt service remains:
$16 million
Downside DSCR:
$19.2 million ÷ $16 million = 1.20x
Nothing changed in the debt schedule.
But the financial cushion reduced from 50% above scheduled debt service to 20%.
That is exactly the type of sensitivity lenders care about.
A Worked LLCR Example
Assume:
- outstanding debt: $100 million
- present value of projected CFADS through loan maturity: $145 million
Then:
LLCR = $145 million ÷ $100 million = 1.45x
Now suppose lender downside assumptions reduce the present value of loan-life CFADS to:
$118 million
LLCR becomes:
1.18x
A project might still have an acceptable near-term DSCR, yet the decline in LLCR reveals deterioration across the loan life.
That is why lenders look beyond a single coverage statistic.
A Worked PLCR Example
Continue the previous example.
Outstanding debt remains:
$100 million
But the project continues operating beyond loan maturity.
Suppose present value of CFADS through the full remaining project life equals:
$170 million
Then:
PLCR = $170 million ÷ $100 million = 1.70x
Compared with:
LLCR = 1.45x
The difference reflects additional discounted CFADS after scheduled loan maturity.
That is the economic value of the debt tail.
But those later cash flows need to remain credible under lender assumptions.
Why a Higher Ratio Is Not Automatically Better
A higher DSCR generally indicates greater cash-flow coverage.
But sponsors should not simply maximise ratios.
A DSCR of 3.00x may indicate very strong coverage.
It may also indicate that the project is using substantially less debt than its economics could potentially support.
Likewise, a highly leveraged structure might produce attractive equity returns but leave insufficient coverage against adverse performance.
The objective is therefore not:
Maximum DSCR
or:
Maximum Debt
It is:
A financing structure that achieves an acceptable balance between debt capacity, resilience, investor returns and lender protection.
What Is a “Good” DSCR?
There is no universal DSCR requirement.
The appropriate ratio depends on the risk characteristics of the transaction.
Relevant factors can include:
- contracted versus merchant revenue;
- counterparty credit quality;
- sector;
- technology;
- project maturity;
- operating history;
- commodity exposure;
- construction risk;
- currency;
- jurisdiction;
- debt tenor; and
- downside volatility.
A project with highly predictable contractual revenue can support a different credit structure from a volatile merchant project.
This is why sponsors should resist copying a DSCR threshold from another transaction.
The contract and underlying risk profile matter.
Lock-Up DSCR vs Default DSCR
Coverage ratios can also operate as financial covenants.
A financing may distinguish between:
Distribution Lock-Up
If DSCR falls below a specified level, distributions to equity may be restricted while debt continues performing.
Event-of-Default Threshold
A more severe threshold may be associated with contractual default consequences.
These are not necessarily the same ratio.
For example, an illustrative structure might contain:
- 1.30x distribution lock-up
- 1.10x default threshold
These figures are examples only, not universal market requirements.
If actual DSCR falls to 1.25x, the project could potentially remain capable of servicing debt while shareholder distributions are restricted.
The financing documents determine the actual consequences.
Why Lenders Care About the Minimum DSCR
Average DSCR can hide a dangerous period.
Consider:
- Year 1: 1.70x
- Year 2: 1.65x
- Year 3: 1.55x
- Year 4: 1.08x
- Year 5: 1.60x
Average coverage may appear relatively comfortable.
But Year 4 is where the lender has a problem.
Project finance debt needs to be serviced when each payment falls due.
Strong cash flow several years later may not solve a liquidity shortfall today.
That is why lenders often focus on:
Minimum DSCR + Average DSCR + LLCR + PLCR + Downside Case
rather than one headline number.
How DSCR Changes Through the Project Lifecycle
DSCR is not necessarily constant.
Construction
Operating DSCR may not yet exist because the asset is not generating operating CFADS.
Ramp-Up
Coverage can initially be weaker as production, occupancy, traffic, utilisation or output builds.
Stabilised Operations
The project may reach its expected operating profile.
Major Maintenance
Coverage may decline if CFADS absorbs significant lifecycle expenditure.
Contract Expiry
Revenue visibility may weaken.
Late Project Life
Production decline, asset degradation or replacement CapEx can become increasingly relevant.
A project finance model should therefore show the coverage-ratio profile through time, not merely one representative year.
DSCR in Renewable Energy Project Finance
Renewable-energy lenders may examine:
- generation forecasts;
- PPA pricing;
- curtailment;
- degradation;
- operating costs;
- major maintenance;
- resource variability;
- counterparty credit; and
- debt tenor.
Downside scenarios might include weaker irradiation or wind resource, higher curtailment or lower merchant pricing.
The lender wants to understand what happens to CFADS and therefore DSCR under those conditions.
DSCR in Mining Project Finance
Mining creates a different coverage challenge.
CFADS can be highly sensitive to:
- commodity prices;
- production;
- grade;
- recovery;
- operating costs;
- sustaining CapEx;
- royalties;
- logistics;
- foreign exchange; and
- mine-life assumptions.
A base-case DSCR that depends on optimistic commodity prices may provide limited lender comfort.
Downside pricing assumptions can therefore materially affect debt capacity.
LLCR and PLCR also require particular care because mine life and production profiles may change as resource and reserve information develops.
DSCR in Infrastructure Projects
Infrastructure projects can offer comparatively predictable cash flows when revenue is supported by arrangements such as:
- availability payments;
- concessions;
- contracted tariffs;
- long-term service arrangements; or
- other contractual revenue mechanisms.
But lenders still need to understand:
- demand risk;
- operating costs;
- lifecycle maintenance;
- inflation;
- counterparty credit;
- availability deductions; and
- concession life.
PLCR becomes particularly interesting when project or concession life extends materially beyond loan maturity.
DSCR in AI Data Centre Finance
AI infrastructure creates a new set of coverage considerations.
A data centre can have significant contracted revenue and still expose lenders to:
- customer concentration;
- power cost;
- utilisation;
- technology refresh;
- replacement CapEx;
- construction delay;
- equipment procurement;
- cooling costs;
- grid availability; and
- contract-renewal risk.
The distinction between asset lives matters.
Buildings, substations and power infrastructure can have long economic lives.
Compute equipment can become obsolete much faster.
CFADS projections therefore need to account for technology-refresh capital requirements rather than assuming every asset produces stable cash flows throughout the financing period.
Why Debt Tail Matters
Suppose:
- loan maturity = Year 15
- project concession ends = Year 22
The project therefore has a:
7-year debt tail
This can provide potential flexibility.
If the project encounters difficulty during the original loan life, lenders may have a period after contractual maturity during which the asset may continue generating cash.
That does not mean lenders automatically extend the loan.
It means the project has potentially valuable residual economic life.
PLCR helps quantify this broader cash-flow horizon.
Why DSCR, LLCR and PLCR Can Tell Different Stories
Imagine:
DSCR = 1.45x
LLCR = 1.18x
PLCR = 1.60x
What might this suggest?
The near-term debt-service position appears stronger than the loan-life position.
LLCR indicates tighter structural coverage before debt maturity.
PLCR improves because meaningful cash flow continues after loan maturity.
That should trigger questions:
- Why does loan-life coverage weaken?
- Is amortisation too aggressive?
- Is there a concentration of debt service?
- Do contracts expire before maturity?
- Is the debt tenor mismatched?
- How reliable is the project tail?
- Could amortisation be restructured?
The ratios do not make the credit decision.
They tell the lender where to investigate.
Coverage Ratios and Downside Cases
A base case is only the beginning of lender analysis.
Project finance models should test adverse scenarios.
Depending on the project, these can include:
- lower revenue;
- reduced production;
- higher OpEx;
- construction delay;
- higher maintenance;
- weaker commodity prices;
- increased power costs;
- customer loss;
- lower utilisation;
- foreign-exchange movements;
- higher interest rates; or
- delayed ramp-up.
A lender may test several variables simultaneously.
This matters because risk rarely arrives one assumption at a time.
A bankable model should demonstrate not only what happens when the project performs as planned, but how the financing behaves when it does not.
DSCR and Distribution Capacity
Sponsors naturally care about equity distributions.
Lenders care about being repaid first.
Financing documents may therefore require coverage conditions before distributions are permitted.
A project might generate cash and still be unable to distribute it if:
- DSCR is below a lock-up threshold;
- reserve accounts are underfunded;
- a default exists;
- required maintenance has not been funded;
- covenant tests fail; or
- other distribution conditions are unsatisfied.
This is another reason why:
Cash in the SPV ≠ Cash available to equity
Understanding the debt waterfall is essential.
Debt Sizing Is Not the Same as Valuation
One of the most common sponsor misunderstandings is assuming that a high project valuation automatically supports a high debt amount.
Debt and equity look at the project differently.
Equity focuses heavily on:
- upside;
- valuation;
- growth;
- exit opportunities; and
- residual returns.
Lenders focus heavily on:
- downside;
- repayment capacity;
- cash-flow timing;
- security;
- covenant headroom; and
- recovery.
Valuation asks what the project may be worth. Debt sizing asks how much contractual debt the project's cash flows can safely repay.
The two should not be confused.
How the Financial Model Should Handle Coverage Ratios
A credible project finance model should make DSCR, LLCR and PLCR transparent.
The model should allow a lender or model auditor to identify:
- CFADS;
- interest;
- scheduled principal;
- debt service;
- debt balance;
- discount rate;
- loan maturity;
- project-life assumption;
- reserve movements;
- minimum DSCR;
- average DSCR;
- LLCR;
- PLCR;
- covenant thresholds;
- lock-up status; and
- downside performance.
Hard-coding a ratio into an output page is not financial modelling.
The ratio should trace directly to underlying project cash flows and the debt schedule.
Common DSCR, LLCR and PLCR Mistakes
Using EBITDA Instead of CFADS
Accounting earnings are not automatically cash available to lenders.
Hiding the Minimum DSCR
An annual average can conceal an individual period of weak coverage.
Ignoring Major Maintenance
Cash required to maintain the asset can materially affect lender coverage.
Using the Wrong LLCR Discount Rate
The financing documents should define the applicable methodology.
Extending Project Life Aggressively
PLCR can look artificially strong when sponsors assume unrealistic terminal project life.
Ignoring Contract Expiry
Cash flow after an offtake or major customer contract ends may carry substantially more risk.
Ignoring Debt Tail Quality
A long project tail is not valuable if the project cannot reliably generate cash during it.
Confusing Covenant and Sizing Ratios
The ratio used to size debt is not necessarily identical to every ongoing covenant requirement.
Failing to Reconcile With Financing Documents
The model should reflect contractual definitions, not generic spreadsheet conventions.
The Projects RH Coverage Ratio Test
Before taking a financial model to institutional lenders, I would ask:
- Is CFADS clearly defined?
- Does CFADS reconcile with the cash-flow statement?
- Does debt service include the correct principal and interest?
- Can we identify minimum and average DSCR?
- Can DSCR be traced period by period?
- Is the LLCR discount methodology explicit?
- Does LLCR stop at the correct debt maturity?
- Does PLCR use a defensible project-life assumption?
- Is the debt tail economically credible?
- Do downside cases recalculate all three ratios correctly?
- Do covenant tests reconcile with the proposed financing terms?
- Does debt sizing remain financeable under lender assumptions?
If those questions cannot be answered quickly, the coverage ratios probably need more work before lender engagement.
Frequently Asked Questions About DSCR in Project Finance
What is DSCR in Project Finance?
DSCR in Project Finance measures Cash Flow Available for Debt Service during a defined period relative to scheduled principal and interest payable during that same period.
The simplified formula is:
DSCR = CFADS ÷ Debt Service
What does a DSCR of 1.50x mean?
A DSCR of 1.50x means the project generates $1.50 of CFADS for every $1.00 of scheduled debt service during the relevant period.
What does a DSCR below 1.00x mean?
It means CFADS during that period is insufficient to meet scheduled debt service from project operating cash flow alone.
What is LLCR?
LLCR, or Loan Life Coverage Ratio, compares the present value of CFADS through the remaining loan life with outstanding debt.
It provides lenders with a longer-term view of debt repayment capacity than periodic DSCR.
What is PLCR?
PLCR, or Project Life Coverage Ratio, compares the present value of projected CFADS through the remaining project life with outstanding debt.
It therefore includes relevant cash flows occurring after loan maturity that LLCR excludes.
What is the difference between DSCR and LLCR?
DSCR examines coverage in a particular debt-service period. LLCR examines discounted coverage across the remaining loan life.
What is the difference between LLCR and PLCR?
The principal difference is the cash-flow horizon.
LLCR stops at loan maturity. PLCR extends through the relevant remaining project life.
Why is PLCR usually higher than LLCR?
When positive CFADS continues after loan maturity, PLCR includes those additional project-tail cash flows while LLCR does not.
Actual results depend on the applicable model definitions and assumptions.
Do lenders use DSCR to size debt?
Yes. DSCR can constrain permitted debt service, influence initial debt capacity and help determine the amortisation profile.
LLCR can also be used in debt sizing and structural credit analysis.
What is debt sculpting?
Debt sculpting shapes scheduled debt repayments around projected CFADS so that the financing targets a defined debt-service coverage level.
What is a good DSCR for project finance?
There is no universal DSCR.
Required coverage depends on project risk, sector, revenue certainty, counterparty strength, jurisdiction, technology, debt tenor and lender requirements.
Which is more important: DSCR, LLCR or PLCR?
There is no single universal answer.
They answer different questions.
DSCR measures periodic payment capacity. LLCR measures loan-life coverage. PLCR measures coverage across the broader remaining project life.
Sophisticated credit analysis considers them together with the contracts, risk allocation and downside cases.
DSCR in Project Finance in One Sentence
DSCR in Project Finance measures periodic debt-service capacity, while LLCR and PLCR extend the lender's analysis across the remaining loan life and project life to assess sustainable debt capacity and long-term credit resilience.
Ratios Do Not Make a Project Bankable
I have always believed that one of the dangers of financial modelling is that numbers can create an illusion of certainty.
A model can calculate:
DSCR = 1.40x
LLCR = 1.50x
PLCR = 1.70x
to two decimal places.
That does not make those cash flows certain.
The real credit work sits behind the ratios:
- Are the revenue assumptions defensible?
- Is production achievable?
- Are the contracts bankable?
- Is maintenance properly funded?
- Is project life realistic?
- Is the debt tail meaningful?
- Are downside assumptions credible?
- Can counterparties perform?
- What happens when the project does not follow the base case?
The ratios translate those answers into financing metrics.
They cannot replace the answers.
That is ultimately why good project finance modelling is not about producing the highest possible DSCR.
It is about showing lenders a financing structure that can withstand scrutiny.
At Projects RH, we help project sponsors prepare robust financial models, capital structures and investment documentation for institutional financing.
Explore our Project Preparation and Investor Readiness Services and learn How Projects RH Works.
Is Your Financial Model Ready for Lender Scrutiny?
If your project is preparing for institutional debt, DSCR, LLCR and PLCR should tell one consistent story about cash flow, debt capacity and downside resilience.
Book a confidential introductory conversation to discuss your project finance requirements, or submit your project information so Projects RH can understand your project's current stage, funding requirement and financial-model priorities.
You can also explore our Project Preparation and Investor Readiness Services and learn How Projects RH Works.
Projects RH | We Make Projects Investor-Ready and Connect Them with the Right Capital
Sources
What to do next
Projects RH prepares the company and the project first, then takes them to investors. The fastest way to find out where you stand is a short call.
Keep reading
Limited-Recourse Project Finance: Sponsors and Lenders
What is Limited-Recourse Project Finance? Learn how project cash flows, SPVs, security and sponsor support define risk for sponsors and lenders.
Project Finance Risk Allocation: Who Carries the Risk?
Who carries construction, market and operating risk? Learn how Project Finance Risk Allocation shapes contracts, bankability and lender confidence.
Conditions Precedent in Project Finance: Before Drawdown
What must happen before lenders release funds? Learn how Conditions Precedent in Project Finance affect financial close, drawdown and execution.